

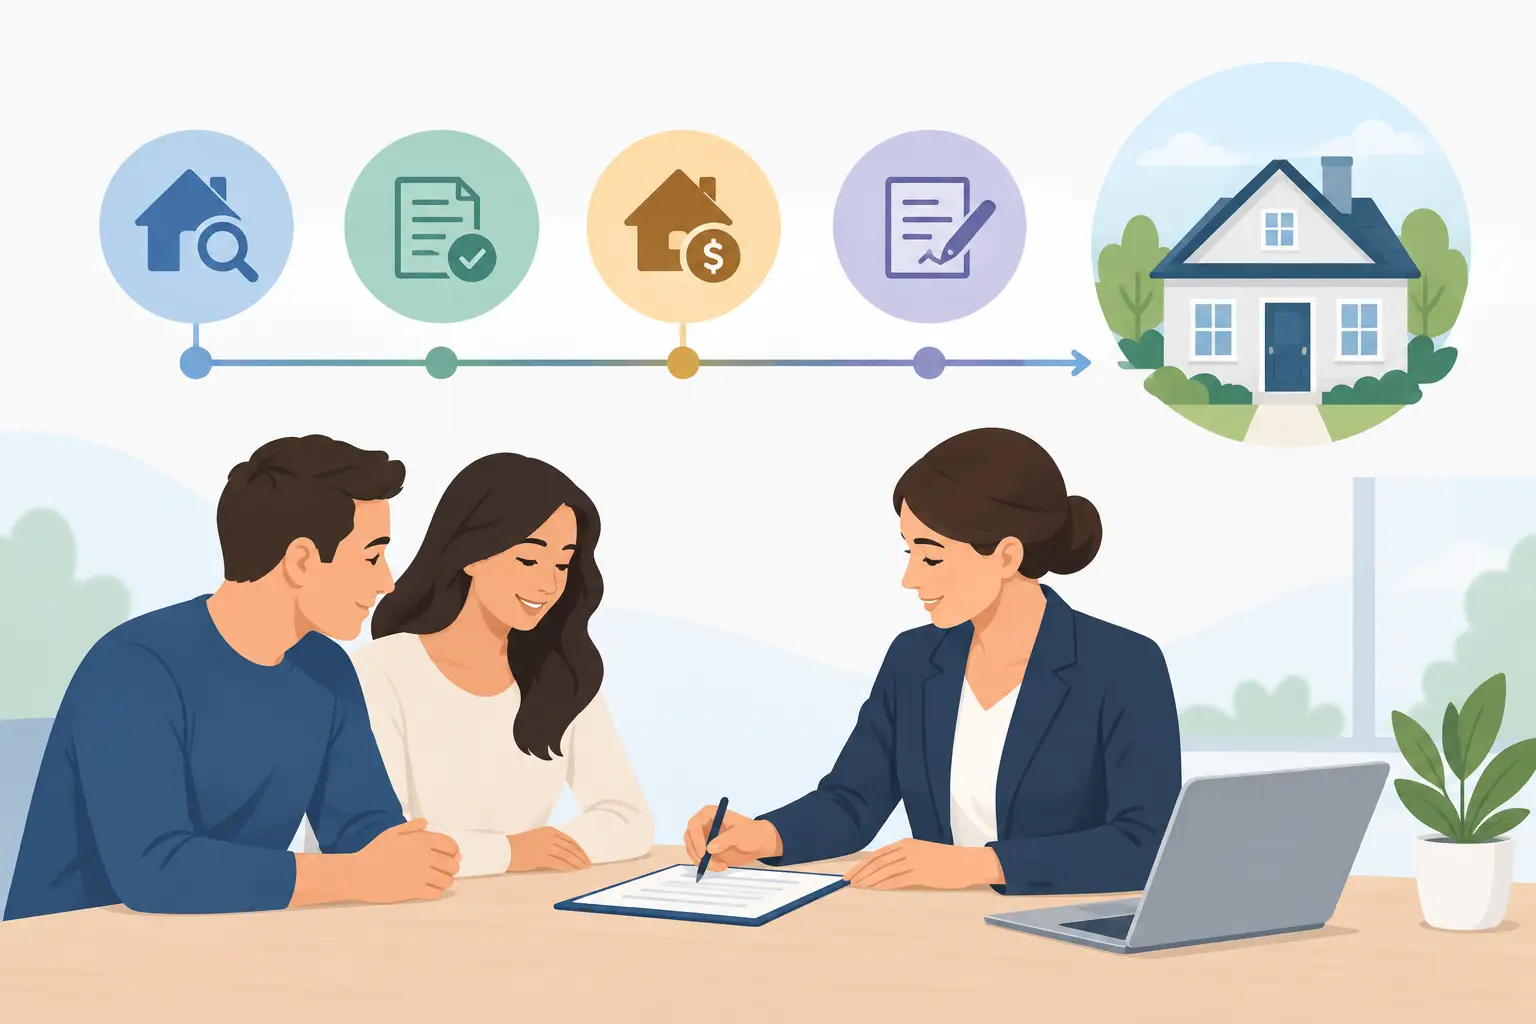
An accepted offer feels like the finish line after weeks or months of searching. In reality, it starts the most time-sensitive part of the purchase: the home buying closing timeline. Between contract signatures and getting the keys, your financing, inspections, appraisal, title work, and final documents all need to come together on schedule.
For many financed purchases, closing takes about 30 to 45 days after the offer is accepted. A cash purchase may close faster, while a transaction involving repairs, a complex loan file, or a tight appraisal can take longer. The goal is not simply to close quickly. It is to keep the property decision and financing decision aligned so there are no late surprises.
A typical home buying closing timeline
Every contract has its own deadlines, and requirements vary by state, loan type, and property. Still, most closings follow a recognizable sequence. Several steps happen at the same time, which is why organized communication matters.
Days 1-3: Contract, deposit, and loan application
Once the seller accepts your offer, the purchase agreement becomes the roadmap. It identifies the target closing date, earnest money deadline, inspection period, financing contingency, and other terms that protect both parties.
You will usually send your earnest money deposit to the designated escrow or title party shortly after the contract is signed. If you were preapproved, your mortgage professional will update your application with the signed contract and begin processing the loan. Be ready to provide current pay stubs, bank statements, identification, tax returns if requested, and explanations for any large deposits or recent credit changes.
This is also the time to avoid opening new credit accounts, financing furniture, changing jobs, or moving money between accounts without first discussing it with your mortgage professional. Even sensible financial decisions can create documentation questions late in the process.
Days 3-10: Inspections and early due diligence
The home inspection is different from an appraisal. An inspector evaluates the home's visible condition and identifies potential concerns with systems such as the roof, foundation, electrical, plumbing, HVAC, and appliances. Depending on the property and your location, buyers may also choose specialized inspections for pests, septic systems, wells, radon, or mold.
After reviewing the results, you may move forward as planned, request repairs or a credit, renegotiate when the contract allows it, or withdraw under an applicable inspection contingency. This is often one of the most active parts of the timeline because repair discussions need to be resolved before later deadlines are affected.
A home does not need to be perfect to be a sound purchase. The practical question is whether the findings change the home's value, safety, expected maintenance costs, or your willingness to proceed. Your real estate and mortgage teams should understand the outcome, particularly if a seller credit or contract amendment affects your financing.
Days 7-21: Appraisal, title work, and underwriting
The lender orders an appraisal to confirm that the home's value supports the loan amount. The appraiser compares the property with recent local sales and considers its condition and features. If the appraised value meets or exceeds the contract price, the loan can continue without an appraisal-related change.
If the appraisal is lower than the purchase price, the transaction may need more discussion. The buyer can bring in additional funds, the seller can lower the price, the parties can negotiate another solution, or the buyer may use an appraisal contingency if included in the contract. There is no single right answer. It depends on the buyer's budget, market conditions, the strength of the comparable sales, and the long-term value of the home to that buyer.
At the same time, the title company or attorney examines public records to confirm ownership and identify liens, judgments, easements, or other items that must be addressed. Title work can be routine, but it can take longer when there are old liens, estate issues, boundary questions, or multiple owners involved.
Your mortgage file also moves through underwriting. Underwriting verifies that the borrower, property, income, assets, and loan program meet the lender's requirements. Requests for additional documents are normal. A quick, complete response helps prevent the file from sitting idle.
Days 21-35: Conditional approval and final loan conditions
Many buyers receive a conditional approval before final approval. This means the underwriter has reviewed the file but still needs specific items, such as an updated bank statement, proof of insurance, a letter explaining an employment or deposit detail, or documentation related to a property condition.
This stage is where coordination makes a real difference. A change to the purchase price, a seller credit, repair agreement, or closing date can affect loan disclosures and underwriting. When your real estate representation and mortgage guidance work together, those updates can be reviewed quickly rather than passed through separate, disconnected contacts.
Avoid assuming that a quiet week means everything is finished. Check in, respond promptly to requests, and confirm that insurance and any required repair documentation are in place. Your loan team should tell you when the file is clear to close, meaning the lender has approved it for closing subject to final checks.
The final week: Closing disclosure, walk-through, and signing
For most mortgage loans, you must receive a Closing Disclosure at least three business days before signing. This document shows the final loan terms, projected monthly payment, cash needed to close, and itemized closing costs. Review it carefully and ask questions about anything that differs from your expectations.
A final walk-through usually happens shortly before closing. It is not another inspection. It is your opportunity to confirm that the home is in agreed-upon condition, included items remain, and negotiated repairs have been completed as required.
At closing, you sign the loan and ownership documents, provide the required funds through an approved method, and complete the final steps needed for recording and disbursement. In some states, keys are provided at signing. In others, possession happens after the deed is recorded or at a time specified in the contract.
What can delay a closing?
Most closing delays are manageable when identified early. Common causes include incomplete financial documentation, appraisal issues, inspection negotiations that extend past deadlines, title problems, insurance complications, and last-minute changes to a buyer's employment, credit, or assets.
Some delays are outside a buyer's control. A seller may need more time to complete repairs, an appraiser may have limited availability, or a title issue may require documents from a prior owner. What matters is having a clear next step, an owner for that task, and timely updates for everyone involved.
A rushed closing is not automatically a better closing. For example, a buyer may be able to close faster by waiving certain protections, but that choice carries risk. Decisions about contingencies, repair requests, and additional funds should reflect your comfort level and financial plan, not just a desire to meet an ambitious date.
How to keep your closing on track
The strongest preparation starts before you make an offer. A current preapproval, realistic down payment plan, and understanding of your likely monthly payment create a better foundation for the contract stage. Once under contract, keep your financial picture stable and reply to requests as soon as possible.
Keep copies of documents in one accessible place, including bank statements, pay stubs, tax records, insurance information, and any paperwork related to gifts or large deposits. Before moving money, paying off debt, or making a major purchase, ask how it could affect loan approval. Small changes can lead to extra review when timing is tight.
It also helps to understand who is handling each part of the transaction. Your real estate professional manages the contract, negotiations, and property details. Your mortgage professional manages loan approval and closing figures. The title or escrow party handles title, funds, and closing documents. With OPEAM Group, real estate and mortgage guidance are coordinated under one roof, helping buyers keep those connected decisions moving in the same direction.
The most useful question throughout the process is not simply, “Are we still on track?” Ask what is due next, who needs it, and what could change the closing date. That habit gives you time to solve small issues before they become moving-day problems.